Use the Holiday Test and 20–30% Rule to Choose Discretionary vs Systematic
For most developing traders, a rules-first systematic approach, or a structured hybrid, is the safer and more testable path. Elite discretionary trading rewards rare pattern recognition built over years, not something you can shortcut. If you’re part-time, new, or still building conviction in your edge, lean systematic first. Below, you’ll find the side-by-side breakdown, the research behind it, and a plan to test your style before you risk real money.
TL;DR:
- Systematic trading benefits from repeatable rules that can be tested across large samples, making it suitable for traders with limited time or evolving confidence.
- Discretionary trading can capture value from unforeseen market shifts but often suffers from inconsistent execution and capacity limitations.
- Empirical research shows no decisive performance difference between styles once volatility and factor exposures are adjusted, emphasizing execution discipline over style choice.
- Hybrid approaches that automate signals, include discretionary filters, and lock risk management demonstrate the most potential for practical success.
- Beginners should start with systematic rules, test thoroughly before live trading, and track discretionary overrides to prevent degradation of their strategy.
Table of Contents
- Discretionary vs Systematic Trading: A Quick Comparison
- The Real Trade-Offs: Strengths, Weaknesses, and Failure Modes
- What the Research Actually Shows
- Structured Discretion: The Hybrid Blueprint That Actually Works
- How to Choose the Style That Fits Your Life
- Testing Your Style Before You Trade It Live
- Why I’d Bet on Rules First, Discretion Second
- Build Your Trading Rules With Profitomics Templates
- Sources
- FAQ
Discretionary vs Systematic Trading: A Quick Comparison
Systematic trading runs on pre-specified rules: entry, exit, and position size are decided in advance and coded or written down before a single trade happens. Discretionary trading strategies let the trader make in-the-moment calls based on chart reading, news flow, or experience. Mechanical trading systems sit at the far end of that same spectrum. Where systematic often allows a human to flip a switch or add a filter, mechanical systems run with zero human override once launched.
The cleanest way to tell them apart isn’t philosophy, it’s a simple thought experiment. Ask: would this strategy still place the same trades if the trader went on a two-week vacation and someone else executed the signals? If yes, it’s systematic. If the outcome depends on who’s sitting at the desk that day, it’s discretionary. This holiday test, sometimes called the reproducibility test, is one of the fastest ways to audit your own strategy.
Each style tends to shine under different conditions:
- Systematic trading excels in trending, liquid markets with consistent volatility, where rules can be back tested across large samples.
- Discretionary trading tends to earn its keep in regime shifts, breaking news, or thin markets where no historical dataset captures the current situation.
- Mechanical systems perform best when discipline, not insight, is the limiting factor for the trader running them.
- Hybrids aim to capture rule-based consistency while leaving room for a human veto when something looks structurally wrong.
Wikipedia’s overview of systematic trading traces the approach back to early trend-following commodity pools, and the core idea hasn’t changed: remove the trader’s mood from the decision.
The Real Trade-Offs: Strengths, Weaknesses, and Failure Modes
Systematic trading’s biggest structural advantage is repeatability. Because the rules are fixed, you generate clean statistical samples you can actually test, and results scale without needing more of your personal attention. That same rigidity is also the risk. Backtests overfit historical noise more often than traders admit, and when too many funds converge on similar rulesets, crowding can trigger fast, correlated losses. The August 2007 quant sell-off is the textbook case: multiple systematic funds unwound similar positions simultaneously, and forced deleveraging turned an orderly correction into a rout.
Discretionary trading strategies offer something systems can’t: the ability to weigh context a rulebook never anticipated, a surprise central bank statement, a sudden liquidity gap, a sector-wide narrative shift. A skilled discretionary trader reading that correctly in real time can capture value no backtest would have flagged in advance. The cost shows up in consistency. Execution varies trade to trade even for the same trader, and it’s genuinely hard to prove whether last year’s returns came from skill or from a lucky stretch. Discretionary books also hit capacity limits faster, since a single person’s attention span caps how much can be managed well.
One statistic worth sitting with: empirical comparisons of more than 9,000 macro and equity hedge funds found that once you adjust for volatility and factor exposure, systematic and discretionary performance converges, with systematic edging out slightly in macro strategies and discretionary sometimes ahead in equities.
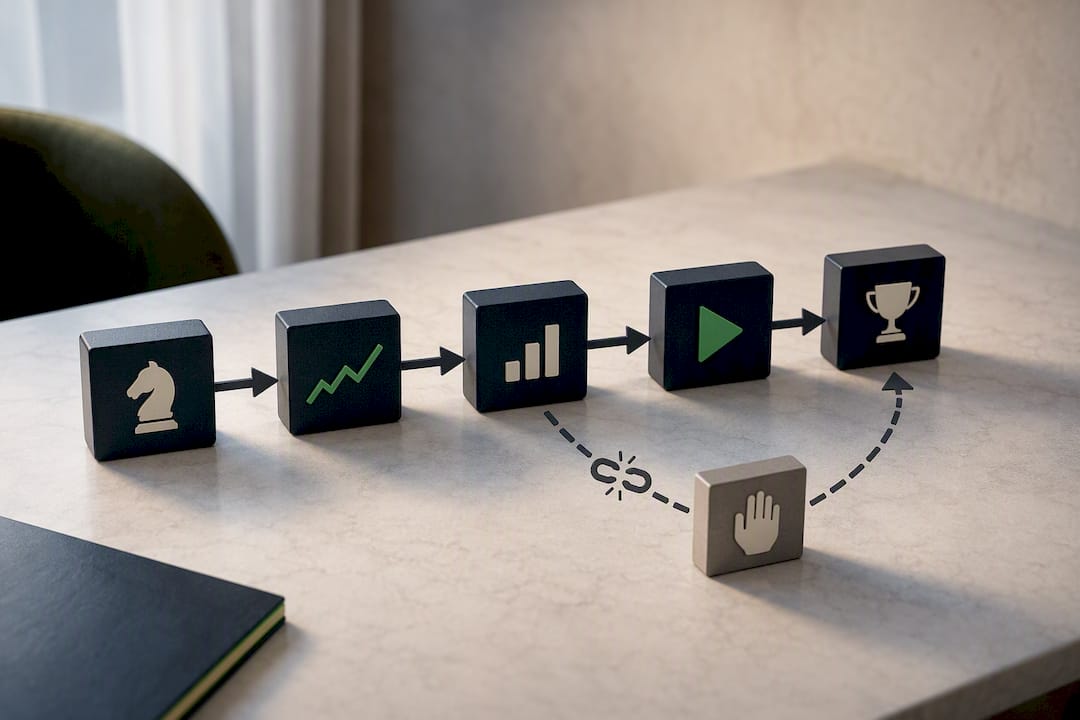
The most dangerous zone isn’t either pure style. It’s the trader who builds a systematic strategy, backtests it carefully, then quietly overrides it “just this once” during live trading. That single override breaks the link between your backtest and your live results. You lose the statistical cleanliness of systematic trading, and you gain none of the accountability structure that makes discretionary trading work when it’s done deliberately. It’s the worst of both worlds, dressed up as flexibility.
What the Research Actually Shows
The most rigorous evidence available is not comforting to purists on either side. Academic work by Campbell Harvey and colleagues found that after adjusting for volatility and factor exposures, systematic and discretionary hedge funds produce broadly similar risk-adjusted performance, with the edge shifting by asset class rather than by philosophy.
Neither style holds a decisive, universal performance advantage once you strip out volatility and factor bets. The difference that matters more is how consistently a trader (or fund) executes their chosen style over time.
That finding reframes the whole “discretionary vs systematic trading” debate. It’s less about which camp wins and more about execution discipline within whichever camp you pick.
A concept worth understanding here is the Fundamental Law of Active Management, often expressed as Information Ratio ≈ IC × √BR, where IC is your skill (information coefficient) and BR is breadth, the number of independent bets you place. The practical takeaway:
- A discretionary trader might have high per-call skill but only place 20 to 30 meaningful trades a year.
- A systematic strategy with modest per-call skill but 2,000 independent signals a year can post a comparable or better risk-adjusted return, purely because breadth compounds.
- This is why quant desks obsess over scale rather than conviction on any single trade.
The obvious caveat: these studies aggregate across many funds and years. They tell you about averages, not about what will happen to your specific account with your specific risk tolerance. Treat the research as a guide to structural tendencies, not a guarantee for any individual trader.
Structured Discretion: The Hybrid Blueprint That Actually Works
The architecture practitioners return to again and again looks like this: systematic signal generation, a discretionary filter, then mechanical risk management. The system finds and ranks opportunities. The human decides whether to take the trade. But once a trade is live, the exit rules are fixed and non-negotiable.
- Automate signal generation. Let a coded or rules-based process surface candidates, removing the temptation to chase whatever looks exciting that morning.
- Add a bounded discretionary filter. The trader can pass or veto a signal based on context, but cannot invent new trades outside the system’s output.
- Lock risk management down completely. Position sizing, stop-loss placement, and max daily loss should never be subject to in-the-moment judgment. Review stop-loss discipline and a risk management checklist before you trade live size.
- Track your override rate monthly. If you’re vetoing more than roughly 20 to 30% of signals, or only vetoing the scary-looking ones, your discretion is likely degrading the system rather than improving it.
Pro Tip: Log every override with a one-line reason before you see the outcome. Reviewing that log monthly is the single fastest way to catch selective veto bias before it costs you real money.
How to Choose the Style That Fits Your Life
Start with an honest inventory, not a preference. Ask yourself five questions: How many hours can you actually dedicate per week? Can you code, or are you comfortable using existing platforms and templates? How much capital are you deploying, and what’s your real tolerance for a losing streak? Do you have a documented edge, or are you still discovering one? How long is your learning horizon, weeks or years?
Map your answers to a likely fit:
- Part-time retail traders with a day job and limited screen time usually do better with systematic or mechanical rules they can set and check, not babysit.
- Hobbyists building quant skills benefit from a mostly systematic approach with a small discretionary layer for position sizing around news events.
- Experienced traders with a thematic edge, someone who deeply understands a sector or macro theme, may justify more discretionary trading strategies, but only after proving consistency on paper first.
- Anyone unsure which camp they’re in should default to structured discretion: mostly rules, narrow judgment windows, hard risk limits.
Watch for red flags that signal you’ve picked the wrong style. Constantly tweaking your system after every losing trade suggests you don’t trust it, a sign you may be temperamentally discretionary. Conversely, if you’re paralyzed without a rulebook and freeze during live decisions, forcing yourself into pure discretionary trading is setting up a bad outcome. Comparing your available time against swing trading versus day trading demands is a useful gut check before committing capital.
Testing Your Style Before You Trade It Live
Run a structured backtest first. Write explicit entry and exit rules, reserve at least 20 to 30% of your data as out-of-sample, and check for look-ahead bias, using information you wouldn’t have actually had at that point in time.
- Backtest with clearly written rules and an out-of-sample holdout, not just an in-sample curve-fit.
- Forward-test on paper for at least 50 to 100 trades before risking real capital, tracking your override rate if any discretion is involved.
- Go live with small size, keeping careful records long enough to hit a meaningful sample, generally several months minimum.
- Run the holiday test periodically: could someone else execute your rules exactly as written while you’re away? If not, tighten the rulebook.
A trend-following framework is a reasonable rules-first template to backtest first, since its logic is simple enough to audit end to end.
Why I’d Bet on Rules First, Discretion Second
Most traders overestimate their discretionary skill because a handful of good calls feel like proof of edge. It rarely is. I’d tell any developing trader to build one small, fully documented rule set, backtest it honestly, then commit to logging every discretionary override you make on top of it. That log is more valuable than the strategy itself, because it shows you, in writing, whether your judgment is adding value or just adding noise. Start narrow. Earn the right to widen your discretion later. Templates like the ones in Stock Market Mastery exist specifically to make that first rule set easier to build without starting from a blank page.
— Kai
Build Your Trading Rules With Profitomics Templates
Profitomics is built for exactly the problem this article walks through: turning “I think I understand systematic vs discretionary trading” into an actual, testable rule set you can run this week. Stock Market Mastery ($47, one-off) gives you the templates and checklists to draft position sizing, stop placement, and entry criteria without hiring anyone or reverse-engineering a strategy from scratch.
If crypto is more your speed, the Crypto Profit System ($37, one-off) applies the same structured approach to digital assets, where discretionary overreaction tends to do the most damage. Both come as instant PDF downloads with companion spreadsheets, so you can start drafting your rule set today rather than waiting on a course schedule. Grab the one that matches your market and start writing your first rules before your next trade.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Man vs. Machine: Comparing Discretionary and Systematic Hedge Fund Performance (Campbell R. Harvey et al.)
- Systematic vs Discretionary Trading, Explained | Quant Memo
- Mechanical Trading System vs Discretionary Trading — Chart Whisperer
- Discretionary vs. Systematic vs. Mechanical Trading Styles | DayTradingToolkit
FAQ
What Is Systematic Trading?
Systematic trading uses pre-specified, written rules for entries, exits, and position sizing, decided before the trade happens rather than in the moment. It’s designed to be reproducible, meaning another person could execute the same rules and get the same trades.
What Are the Four Types of Trading?
Most practitioners break trading styles into discretionary, systematic, mechanical, and hybrid (structured discretion). The distinctions come down to how much human judgment enters the decision and how reproducible the process is once it’s running.
What Does Discretionary Mean in Trading?
Discretionary means the trader makes real-time judgment calls, reading charts, news, or context, rather than following a fixed rulebook. It rewards experience and pattern recognition but makes results harder to reproduce or attribute to skill.
What Is the 3-5-7 Rule in Trading?
Definitions of the 3-5 rule vary across sources and aren’t tied to a single standardized framework, so treat any specific version with caution. It’s generally cited as a risk-scaling guideline rather than a universally agreed rule, and it isn’t a substitute for the position sizing and stop-loss discipline covered in a proper risk management plan.
Should Beginners Start With Systematic or Discretionary Trading?
Beginners generally do better starting systematic, because fixed rules create a testable, reviewable process instead of relying on judgment that hasn’t been proven yet. Once a rule set shows consistency over a real sample size, adding a bounded discretionary filter, structured discretion, is a reasonable next step.